

A concentrated, stock-picking fund that is managed with a strong sense of risk. The portfolio is composed of quality stocks and mis-priced opportunities, with the team investing in companies creating shareholder value. Within its sector, the fund features in our ‘Larger-Cap, Blend’ category.
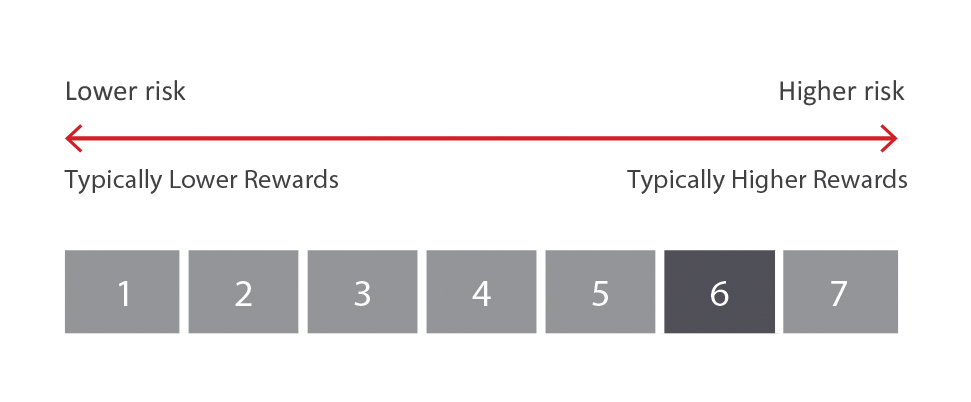
The fund’s KIID Synthetic Risk and Reward Indicator (SRRI) is 6. This is a regulatory measurement that is, where possible, calculated from the volatility of its weekly performance over a five-year period. A score of 6 means the fund’s historic volatility is between 15% and 25%.
The fund’s risk score of 6 is common within the sector. Over time, the fund’s volatility is similar to the index, which is in keeping with the manager’s risk-aware approach, and particularly his focus upon controlling the tracking error. Different share classes could have differing SRRI scores.
The fund is managed by Tokyo-based Portfolio Manager and Head of Japanese Equities, Junichi Inoue. He has covered the Japanese market since 1998 and has managed the fund since 2016. He is supported by Portfolio Manager, Yunyoung Lee, who is based in Singapore, and Associate Portfolio Manager, Yusuke Suzuki, who is based in Tokyo. In terms of stock coverage, Mr Inoue focuses primarily on large-cap companies, while the remainder of the investment universe is covered by the other team members. In addition, the team draws on the wider Janus Henderson Central Research Team, which provides research across all global sectors.
The manager believes that strong cash flow returns from capital-efficient businesses will create shareholder value. The team identifies these businesses through an intensive bottom-up stock selection process, and they believe that this, combined with a concentrated portfolio approach, will deliver superior returns.
The portfolio typically comprises around 30 stocks, as the manager believes that this level of concentration ensures that each position has a meaningful influence on the portfolio’s outcome. He invests across the market-cap spectrum, although liquidity considerations preclude investments in very small-cap stocks. Large- and mid-cap stocks can be held in positions of between 3% and 6%, depending on conviction. Smaller companies are held in positions of up to 2%. With the support of the firm’s risk team, care is taken to ensure that no single position, risk or macroeconomic factor dominates the fund’s risk/return outcome. The team also focuses on controlling tracking error at both the underlying stock level and the overall portfolio level.
The bottom-up stock-picking approach aims to identify well-managed businesses that generate free cash flow returns above their cost of capital. The first step in the process is to screen more than 2,000 stocks for ESG and market-cap considerations. The screened stocks are then put through a HOLT process, with particular emphasis on cash flow return on investment (CFROI). The objective is to find companies that have a positive and/or improving CFROI. This produces about 125 stocks, on which the managers conduct intensive fundamental research.
The initial focus is on the company’s business drivers and strategy. The management team is assessed on its use of capital, either to reinvest in the business or to return capital to shareholders through dividends or share buybacks. The team also analyses the management team’s ability to deliver on its strategy by assessing the success of previous business plans, capital-allocation decisions and strategic acquisitions. This narrows the universe to approximately 100 stocks, upon which the team carries out its valuation work. Financial modelling aims to establish an intrinsic value for each business under review and helps them assess the upside opportunity and downside risk. At this point, businesses are considered through two lenses. For quality stocks, which make up at least two-thirds of the portfolio, the managers look for 50% upside over three years and 15% downside. For mispriced opportunities, which make up the balance of the portfolio, they look for a minimum upside of 20% over one year. This leaves around 50 stocks from which to construct a portfolio. The manager makes the final decision on investment cases, also considering other factors such as risk control and the market outlook.
Formal documentation, including the fund prospectus and the KIID, should be sought directly from the asset manager. For ease of reference, a link to the ASSET MANAGER WEBSITE can be found above.
Investment Association sector definition: Funds which invest at least 80% of their assets in Japanese equities.
Read more > Your use of this website is subject to the terms of use set out in the website. By continuing to use our website we will assume that you are happy to receive non-privacy intrusive cookies. Please be aware that if you disable cookies some functionality on the site will not work. Read our cookies policy to find out more about our cookie use and how to disable cookies.
Alternatively, if you are not a financial professional and are seeking financial advice, you may wish to visit unbiased.co.uk to search for a financial adviser.