

An Asia Pacific ex Japan equity fund managed according to a bottom-up approach that relies upon deep company research on a curated universe of stocks. The managers look to understand why conventional wisdom may be wrong, in doing so seeking to invest in companies that are priced at a discount to their true worth. Within its sector, the fund features in our ‘Larger-Cap, Value-Biased’ category.
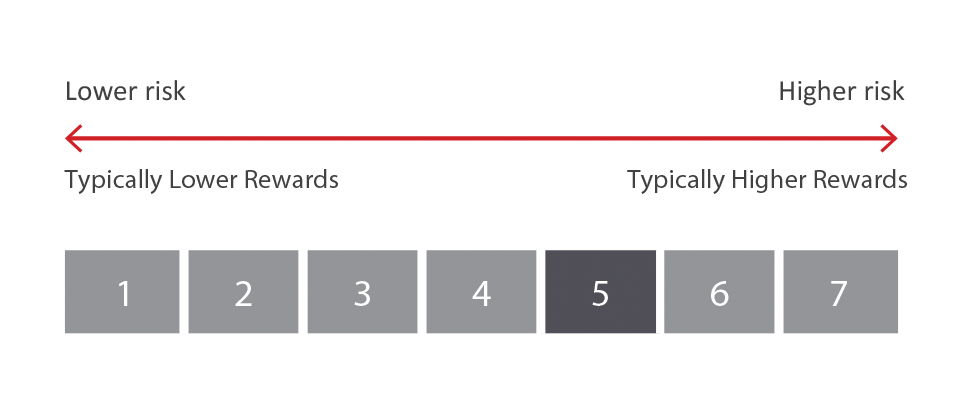
The fund’s KIID Synthetic Risk and Reward Indicator (SRRI) is 5. This is a regulatory measurement that is, where possible, calculated from the volatility of its weekly performance over a five-year period. A score of 5 means the fund’s historic volatility is between 10% and 15%.
The fund’s standard deviation is broadly in keeping with the index. The portfolio is built from the bottom up and therefore it will display sector and country biases. However, the managers only tolerate large active sector bets where they have a specific view, meaning that significant dispersions are possible, but not typical. Over time, we would expect the risk-aware nature of the approach to lead to a volatility outcome that is in keeping with the main index. Different share classes could have differing SRRI scores.
The fund is managed by David Perrett, lead manager and Co-Head of Asia Pacific Equities at M&G. He joined M&G in 2019 and, before this, co-founded the boutique investment firm, Port Meadow Capital Management, with Carl Vine in 2014. Deputy manager, Carl Vine, joined M&G in 2019 as Co-Head of Asia Pacific Equities and is responsible for managing a number of Japanese equity portfolios. They lead a small team of fund managers, investment analysts and dedicated supports based in London, Tokyo, Singapore, Hong Kong and Mumbai.
The managers seek attractive relative returns by identifying exploitable gaps between a share price and what they consider to be the true value of a listed equity. They believe in concentrating their efforts around a pre-defined universe with the aim of developing in-depth and extremely well-informed perspectives on companies compared to other participants in the market. They believe that their skills lie not in superior forecasting, but in the superior pricing of risk.
The fund typically holds between 50 to 80 stocks and active positions typically range from 1% to 5%. The nature of the fund’s approach can lead to sector and country biases, but large sector positions are only made when they have a specific and convicted view. Portfolio construction and position sizing is considered and analysed very carefully. The team sets a desired level of outperformance against the fund’s benchmark. They use this targeted ‘reward’ to inform a target level of ‘risk’ for the fund and then seek to allocate this risk budget to high-conviction, non-correlated, differentiated investments.
The managers are valuation-sensitive, fundamental investors and they focus upon companies where they have good reason to believe they have a superior perspective. Their approach is based on the principle that there are four key elements to the so-called ‘investment problem’: Independence; Conviction; Fallibility; and, Uncertainty. Independence refers to the need to produce differentiated investment ideas to succeed. Conviction is important because markets and competing narratives will test their resolve. Fallibility is the acknowledgement that mistaken thinking and/or bad luck are unavoidable. Uncertainty is at the heart of the investment conundrum, as most of the value within securities lies in an unforecastable future.
Against this philosophical backdrop, they work from a carefully curated investment universe of 450 stocks and focus upon maintaining a deep knowledge of the ecosystem within and surrounding a company. They favour more stable business models with relatively few competitors and limited operational data points with a view to building detailed understanding. While quantitative screens are part of the process, most of their ideas emanate from their qualitative research, whereby ongoing dialogue with the companies in their universe is considered critical. Ultimately, they are seeking to understand their risks of ownership of the businesses and how revenues, earnings and corporate strategy might respond to different scenarios. They maintain expected values for the companies in their universe, flexing their valuation approach according to the business in question. The portfolio is built from stocks where there are large gaps between the current price and the team’s expected value, and which therefore incorporate a good margin of safety.
Formal documentation, including the fund prospectus and the KIID, should be sought directly from the asset manager. For ease of reference, a link to the ASSET MANAGER WEBSITE can be found above.
Investment Association sector definition: Funds which invest at least 80% of their assets in Asia Pacific equities and exclude Japanese securities.
Specific sector note:
Up to 5% (but no more than 5%) of the total assets of the fund can be invested in Japanese equities to allow flexibility for corporate actions, for example.
Your use of this website is subject to the terms of use set out in the website. By continuing to use our website we will assume that you are happy to receive non-privacy intrusive cookies. Please be aware that if you disable cookies some functionality on the site will not work. Read our cookies policy to find out more about our cookie use and how to disable cookies.
Alternatively, if you are not a financial professional and are seeking financial advice, you may wish to visit unbiased.co.uk to search for a financial adviser.